Where to start
We have been taught to look at retirement as a destination
When in reality, it is more of a journey. Here are the fundamentals Linda covers with every client — open any topic for the full guide.
Keeping your money safe
Imagine approaching retirement and watching your portfolio be cut in half. Maybe you don't have to imagine, because it happened to you in 2008. While there are no surefire ways to avoid a stock market crash, there are some things you can do to reduce the likelihood that you will suffer the consequences of one in the future. Here's how to protect your savings from a significant downturn in the financial markets.
Read the full guide
Legalities of aging
Your estate planning should accomplish three purposes: protect yourself; protect your family; and give you peace of mind. How you do that varies, so knowing the fundamentals is the first step. Estate planning is more than just a will, since you should plan for possible incapacity as well as death.
Read the full guide
Maximizing Social Security
For many Americans, Social Security benefits are the bedrock of retirement income. It is the foundation on which your retirement finances are built. Maximizing that stream of income is critical to funding your retirement dreams. The rules for claiming benefits can be complex, and recent changes to Social Security rules created a lot of confusion. But this guide will help you wade through the details. By educating yourself about Social Security, you can ensure that you claim the maximum amount to which you are entitled.
Read the full guide
It’s all about income
You'll most likely spend your pre-retirement years accumulating assets through saving and investing. Once you hit retirement, the idea is to use these assets in a way that will provide you with a cash flow that will try to match your spending. Having assets during retirement is a great thing, but it you can't effectively draw on your wealth to satisfy your spending in retirement, it won't adequately serve your retirement needs.
Read the full guide
The long-term care dilemma
No one wants to think about a time when they might need long-term care. So planning ahead for this possibility often gets put off. Most people first learn about long-term care when they or a loved one need care. Then their options are often limited by lack of information, the immediate need for services, and insufficient resources to pay for preferred services. Planning ahead allows you to have more control over your future.
Read the full guide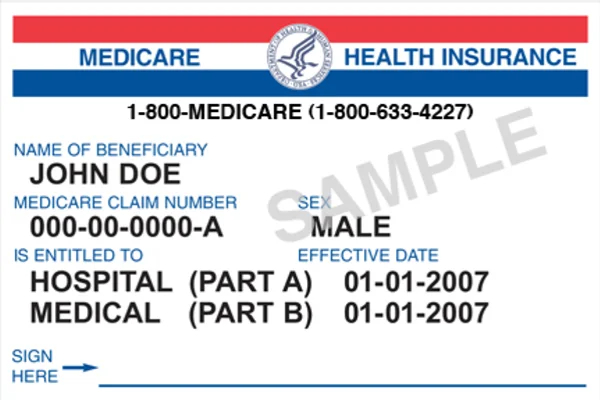
Navigating Medicare
Signing up for Medicare is another major retirement milestone. To qualify for Medicare you must be 65 years old or on Social Security Disability for 2 years. Under Medicare, pre-existing conditions no longer hinder your ability to get insurance. And as long as you continue to pay your premiums (which are usually deducted from your Social Security check), you are guaranteed health coverage that will last for the rest of your life. Unlike other health insurance, Medicare coverage is divided into four parts: A, B, C and D. This allows you to choose which parts you want and avoid duplicating coverage from other insurance.
Read the full guide
Caregiving for aging parents
Caregiving responsibilities can influence individuals' retirement decisions and their post-retirement well-being. The effect of caregiving responsibilities on retirement decisions depends upon the relative balance between care-related time demands and financial needs due to care recipients' illness or disability, as well as on factors such as gender or care relationship. Men seem more inclined to adjust retirement decisions to mesh with financial obligations; women, who usually carry the main responsibility for hands-on care, tend to respond to care-related time pressures.
Read the full guideNot sure where to start?
Book a one-on-one conversation and Linda will walk you through it.